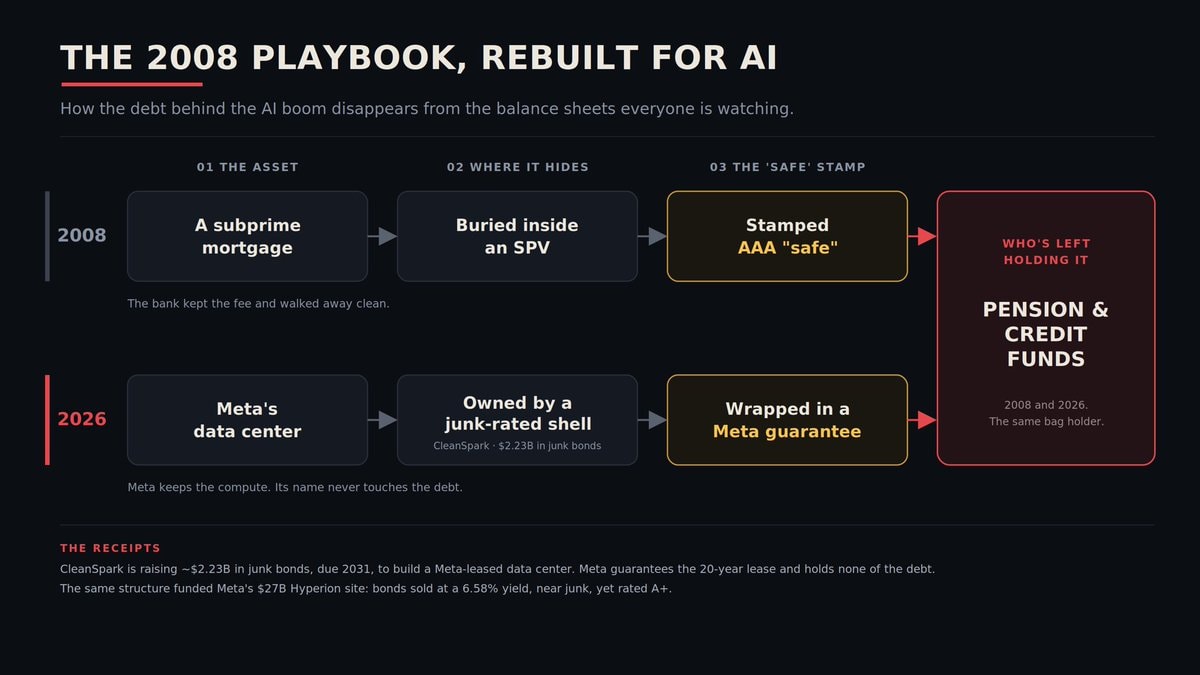
@tim_officialThe AI boom is running the same playbook that blew up the world in 2008: Bury the risk where nobody's looking, slap a safe label on it, and make sure your name isn't on it when it breaks. Here's the machine, step by step, because it's worth understanding before this whole thing blows up: In 2008, the banks didn't keep the risky loans they made. They bundled them, paid a rating agency to stamp them safe, and sold them off to pension funds and everyone else. The banks kept the fees. When the housing underneath went bad, the loss landed on whoever was holding the paper. The people who built the bomb were nowhere near it when it went off. Now look at what the AI giants are doing with their buildout: Meta has committed around $600 billion to AI infrastructure. A company that size could borrow the money itself at some of the cheapest rates on Earth. But debt on your own balance sheet is visible, and visible debt scares your investors. So the debt goes somewhere else. This week we found out where… A Bitcoin miner called CleanSpark is borrowing roughly $2.23 billion in junk bonds to build a data center in Georgia. The tenant who will fill it is Meta. Meta guarantees the rent for 20 years, and that guarantee is what lets those junk bonds get sold as something safe. But the debt itself sits on the miner's books, inside a shell company built for the deal, and nowhere near Meta's. Look closely at what that miner is: Its stock trades near the lowest point of its year. It has never earned a single dollar from AI. It still digs up Bitcoin to keep the lights on. And it is now the party holding billions in high-yield debt so that one of the most valuable companies on Earth doesn't have to. That is the 2008 move exactly. The strong party keeps the asset and the upside. The risk gets walked across the street and handed to someone far weaker, wrapped in a guarantee that makes the whole thing look safe. And this is not just one strange deal. Meta financed a separate $27 billion site through a private credit fund, on bonds that paid a near-junk yield even after they were rated A plus. Other AI landlords are raising billions more in convertible notes and high-yield paper. The entire physical layer of the AI boom is being funded in the riskiest corner of the credit market, one guaranteed lease at a time. But why would you even care? Every one of these deals rests on the same promise: That Big Tech keeps paying the rent no matter what happens. So the moment the AI trade turns, all of these deals turn at once, because they were leaning on the same small handful of guarantees. That is the EXACT correlation nobody bothered to price in 2008. And yes, Meta is a real company with real money, and a guaranteed lease is nothing like a subprime mortgage. But the structure underneath is identical, and the structure is what decides who survives when the cycle breaks. So when someone tells you the AI boom is safe because the tech giants are paying out of pocket, understand what they're missing: The debt is still there. It has only been moved into shell companies and junk bonds and other people's names, so it never shows up where anyone is looking. And when it breaks, the loss lands where it always lands: On the pension funds and credit funds that bought the safe label. They are the same people who paid for 2008 the first time. Believe in the AI trade or not, but the facts are undeniable.
查看原帖
还没有评论。来抢沙发吧!